Lease to Own vs Car Loan in the UAE: 2026 Comparison Guide for Abu Dhabi & Dubai Residents

Deciding on a lease to own vs car loan in the UAE? This 2026 guide for Dubai & Abu Dhabi shows how to skip the 20% down payment and drive your dream car.
What if the 20% down payment your bank demands is actually a hidden tax on your mobility? Saving AED 45,000 for a deposit is a massive hurdle when you're also managing rising rents in Dubai or settling into a career in Abu Dhabi. You likely feel that the dream of ownership is stalled by strict salary certificate rules and the fear of long-term debt. Deciding between a lease to own vs car loan uae is no longer just about interest rates; it's about keeping your cash liquid in a fast-paced market.
Discover whether a traditional bank loan or a flexible lease-to-own program is the fastest, most cost-effective path to your next car. We'll show you how to bypass rigid financial barriers and secure a vehicle without a massive upfront cash outlay. This guide breaks down the total cost of ownership, the 5 specific documents required for 2026, and how to drive away with confidence. Your journey to a premium vehicle starts with making the smartest financial choice for your lifestyle.
Key Takeaways
- Navigate the "20% Down Payment Rule" and understand the specific salary requirements demanded by banks across the Emirates.
- Keep your capital liquid for Dubai living by exploring zero-deposit alternatives to traditional vehicle financing.
- Evaluate the financial impact of a lease to own vs car loan uae to determine which path offers the fastest route to ownership.
- Simplify your monthly budget by bundling insurance, registration, and maintenance into one transparent AED-denominated payment.
- Discover how Al Hurr’s premium fleet and hassle-free process transform car ownership into a seamless, high-status experience.
Understanding Car Financing: Lease to Own vs Car Loan in the UAE
Choosing your next vehicle in Abu Dhabi involves more than just picking a model. You must decide how you want to pay for it. The debate of lease to own vs car loan uae residents face often comes down to long term goals versus immediate cash flow. A UAE car loan is a traditional bank-financed purchase. You're the registered owner, but the bank holds a mortgage on the vehicle until you clear the final payment. This means the car's registration card, known as the Mulkiya, will explicitly list the bank as the mortgagee.
Lease-to-own, often called rent-to-own, works differently. It's a long-term rental agreement where a portion of your monthly payment builds equity toward eventual ownership. You don't own the car during the contract period. The rental company maintains the legal title. This model has seen a 12% rise in adoption across Abu Dhabi and Dubai since early 2024. Residents now prioritize flexibility over rigid 60-month bank commitments. For a deeper look at the mechanics, Understanding Vehicle Leasing provides a neutral breakdown of how these global financial structures operate and how they differ from standard hire purchase agreements.
In 2026, the UAE car market is shifting rapidly. High interest rates and a desire for all-inclusive lifestyles drive this change. You want a car that fits your life today, not a debt that weighs you down for five years. Understanding the legal title is crucial. With a loan, the car is yours, but you can't sell it without the bank's permission. With a lease, you're a tenant of the vehicle with a clear, predefined path to becoming the owner. This removes the stress of ownership until you're ready to commit fully.
The Traditional Car Loan Path
UAE banks structure auto finance to favor stability. You'll typically need a minimum salary of AED 5,000 to qualify for most packages. Banks offer two types of interest rates. Flat rates usually range from 2.25% to 4.50%, while reducing rates hover between 4% and 8%. Your Al Etihad Credit Bureau (AECB) score is the gatekeeper here. A score above 700 often unlocks the best rates and faster approvals. Remember that UAE Central Bank regulations require a 20% down payment upfront. This is a significant cash hurdle for many buyers in Abu Dhabi.
- Down Payment: Minimum 20% of the car's value is mandatory.
- Approval Time: Usually takes 2 to 5 business days for processing.
- Ownership: You own the car from day one, subject to the bank mortgage.
The Modern Lease-to-Own Alternative
The lease-to-own model is gaining massive traction because it simplifies your life. It bundles everything into one monthly payment. You don't worry about finding AED 2,000 for annual comprehensive insurance or AED 1,500 for a major service. The rental company handles the registration and maintenance. This all-in-one nature makes budgeting predictable. If your circumstances change, these agreements often provide more fluid exit or upgrade options than a bank loan. You can drive a brand-new SUV this year and switch to a sleek sedan the next without the hassle of the used car market.
- Inclusive Costs: Insurance, service, and registration are typically covered.
- Low Entry Barrier: Many providers offer low or no upfront deposits compared to banks.
- Flexibility: Enjoy easy options to return, swap, or upgrade the vehicle.
Experience the freedom of the road without the stress of bank debt. Your journey in Abu Dhabi deserves a solution that matches your pace. Explore your options and choose the path that puts you in the driver's seat on your own terms. Whether you prefer the traditional route or the modern lease, ensure the choice aligns with your 2026 financial goals.
The Realities of Securing a Car Loan in Abu Dhabi and Dubai
Securing a bank loan in Abu Dhabi often feels like a high-stakes hurdle race. While the idea of owning a vehicle is exciting, the financial entry barriers are significant. The Central Bank of the UAE sets strict limits to ensure fiscal stability, which directly impacts your ability to get behind the wheel. When weighing the pros and cons of lease to own vs car loan uae, you must first face the immediate cash requirements that banks demand.
The 20% Down Payment Rule is the first major barrier you'll encounter. You can't finance 100% of a car's purchase price in this market. According to UAE government car loan regulations, banks provide a maximum of 80% of the vehicle's value as a loan. If you're eyeing a premium SUV priced at AED 200,000, you need AED 40,000 ready in your savings account before even walking into the showroom.
Beyond the down payment, your monthly income dictates your eligibility. Most Abu Dhabi banks, such as ADCB or First Abu Dhabi Bank (FAB), require a minimum monthly salary of AED 5,000. However, for many luxury models, this threshold jumps to AED 10,000 or higher. Your Al Etihad Credit Bureau (AECB) score acts as your financial passport. A score below 600 often leads to immediate rejection, while a high score helps you secure "flat" interest rates, which currently hover between 2.25% and 4.5% depending on the bank's appetite for risk.
Don't forget the hidden costs that inflate your initial investment. You'll likely pay a processing fee of 1% of the loan amount, usually capped at AED 2,625. Banks also require mandatory comprehensive insurance, which typically costs between 2% and 4% of the car's total value annually. These "small" extras can easily add another AED 5,000 to AED 8,000 to your startup costs.
Mandatory Documentation for Bank Finance
The paperwork trail is extensive and non-negotiable. You'll need to provide original salary certificates, three to six months of stamped bank statements, and clear copies of your UAE Residence Visa and Passport. This process is particularly grueling for new expats. If you've been in the country for less than six months, most banks won't even look at your application. They want to see a stable history of "salary transfer" before they trust you with a multi-year loan. If you need a vehicle immediately without the red tape, exploring long-term rental alternatives can save you weeks of administrative stress.
Long-term Financial Commitment
A car loan is a marathon, not a sprint. The maximum tenure allowed in the UAE is 60 months. While this lowers your monthly installment, it ties you to a rigid financial schedule for five years. If your circumstances change and you decide to leave the UAE before the loan is paid off, the bank can technically request a travel ban until the balance is settled or the car is sold to cover the debt.
Depreciation is the silent cost that many buyers ignore. A brand-new car in Dubai or Abu Dhabi can lose 15% to 20% of its market value the moment it's registered. By the end of a 60-month term, you might find that the car's resale value is barely enough to cover the final interest payments. This reality makes the choice of lease to own vs car loan uae a critical decision for your long-term wealth. Owning an asset that loses value daily while paying interest on it requires careful calculation.
Why Lease-to-Own is the Tactical Choice for UAE Expats
Choosing between lease to own vs car loan uae often comes down to how you want to manage your cash flow in a high-growth environment like Abu Dhabi. Traditional bank loans in the UAE strictly require a 20% down payment as per Central Bank regulations. On a standard 150,000 AED SUV, you must provide 30,000 AED upfront. Lease-to-own models through Al Hurr allow you to bypass this massive initial hit. You keep your capital liquid for housing deposits or school fees while driving the vehicle you need today. It's a strategic move that prioritizes your immediate lifestyle without draining your savings.
Approval processes for bank loans are notoriously rigid. Most local banks demand a minimum of 3 to 6 months of employment history and a confirmed salary transfer to their institution. If you just arrived on a new residency visa or work as a freelancer, you'll likely face immediate rejection. Lease-to-own providers focus on your current ability to pay rather than lengthy historical data. This accessibility ensures you aren't stuck using expensive daily rentals or taxis during your first weeks in the country. You get the keys faster and with far less paperwork.
The financial transparency of a bundled monthly fee is a major advantage for any budget-conscious resident. A typical car owner spends roughly 5,000 AED annually on comprehensive insurance and registration renewals. When you factor in the 20% to 30% depreciation hit most vehicles take in their first 12 months, the true cost of ownership becomes clear. Lease-to-own eliminates these surprises. Your single monthly payment covers the car, the insurance, and all registration fees. It turns a volatile expense into a predictable line item in your monthly budget.
Maintenance and Service Peace of Mind
Forget the stress of navigating industrial zones like Mussafah or Al Quoz to find a trustworthy mechanic. Al Hurr manages every aspect of your vehicle’s health. We handle the 10,000 km service intervals and all routine wear-and-tear items. If a warning light appears during a 48-degree Celsius summer afternoon, our 24/7 roadside assistance team responds immediately. You stay cool in the office while we handle the logistics of the repair. It's a seamless experience designed for busy professionals.
Flexibility and Upgradability
Expat life is dynamic, and your vehicle should reflect that. You might start with a compact sedan for city commuting and realize you need a larger 4x4 for desert excursions after a year. When comparing lease to own vs car loan uae, the ability to switch is a game changer. You aren't tethered to a 60-month bank contract that's difficult to exit. After your initial term, simply return the car or upgrade to the latest model. You avoid the headache of the used car market, where private sellers often lose 15% of their car's value just through aggressive low-ball offers from dealers.
Experience the freedom of the road without the long-term debt. Lease-to-own provides a safety net that bank loans simply can't match. If your circumstances change and you need to leave the UAE, the exit process is straightforward and transparent. You aren't left trying to sell a depreciated asset while rushing to catch a flight. It's the ultimate risk mitigation tool for the modern expat.
Side-by-Side Comparison: Which Path Suits Your Journey?
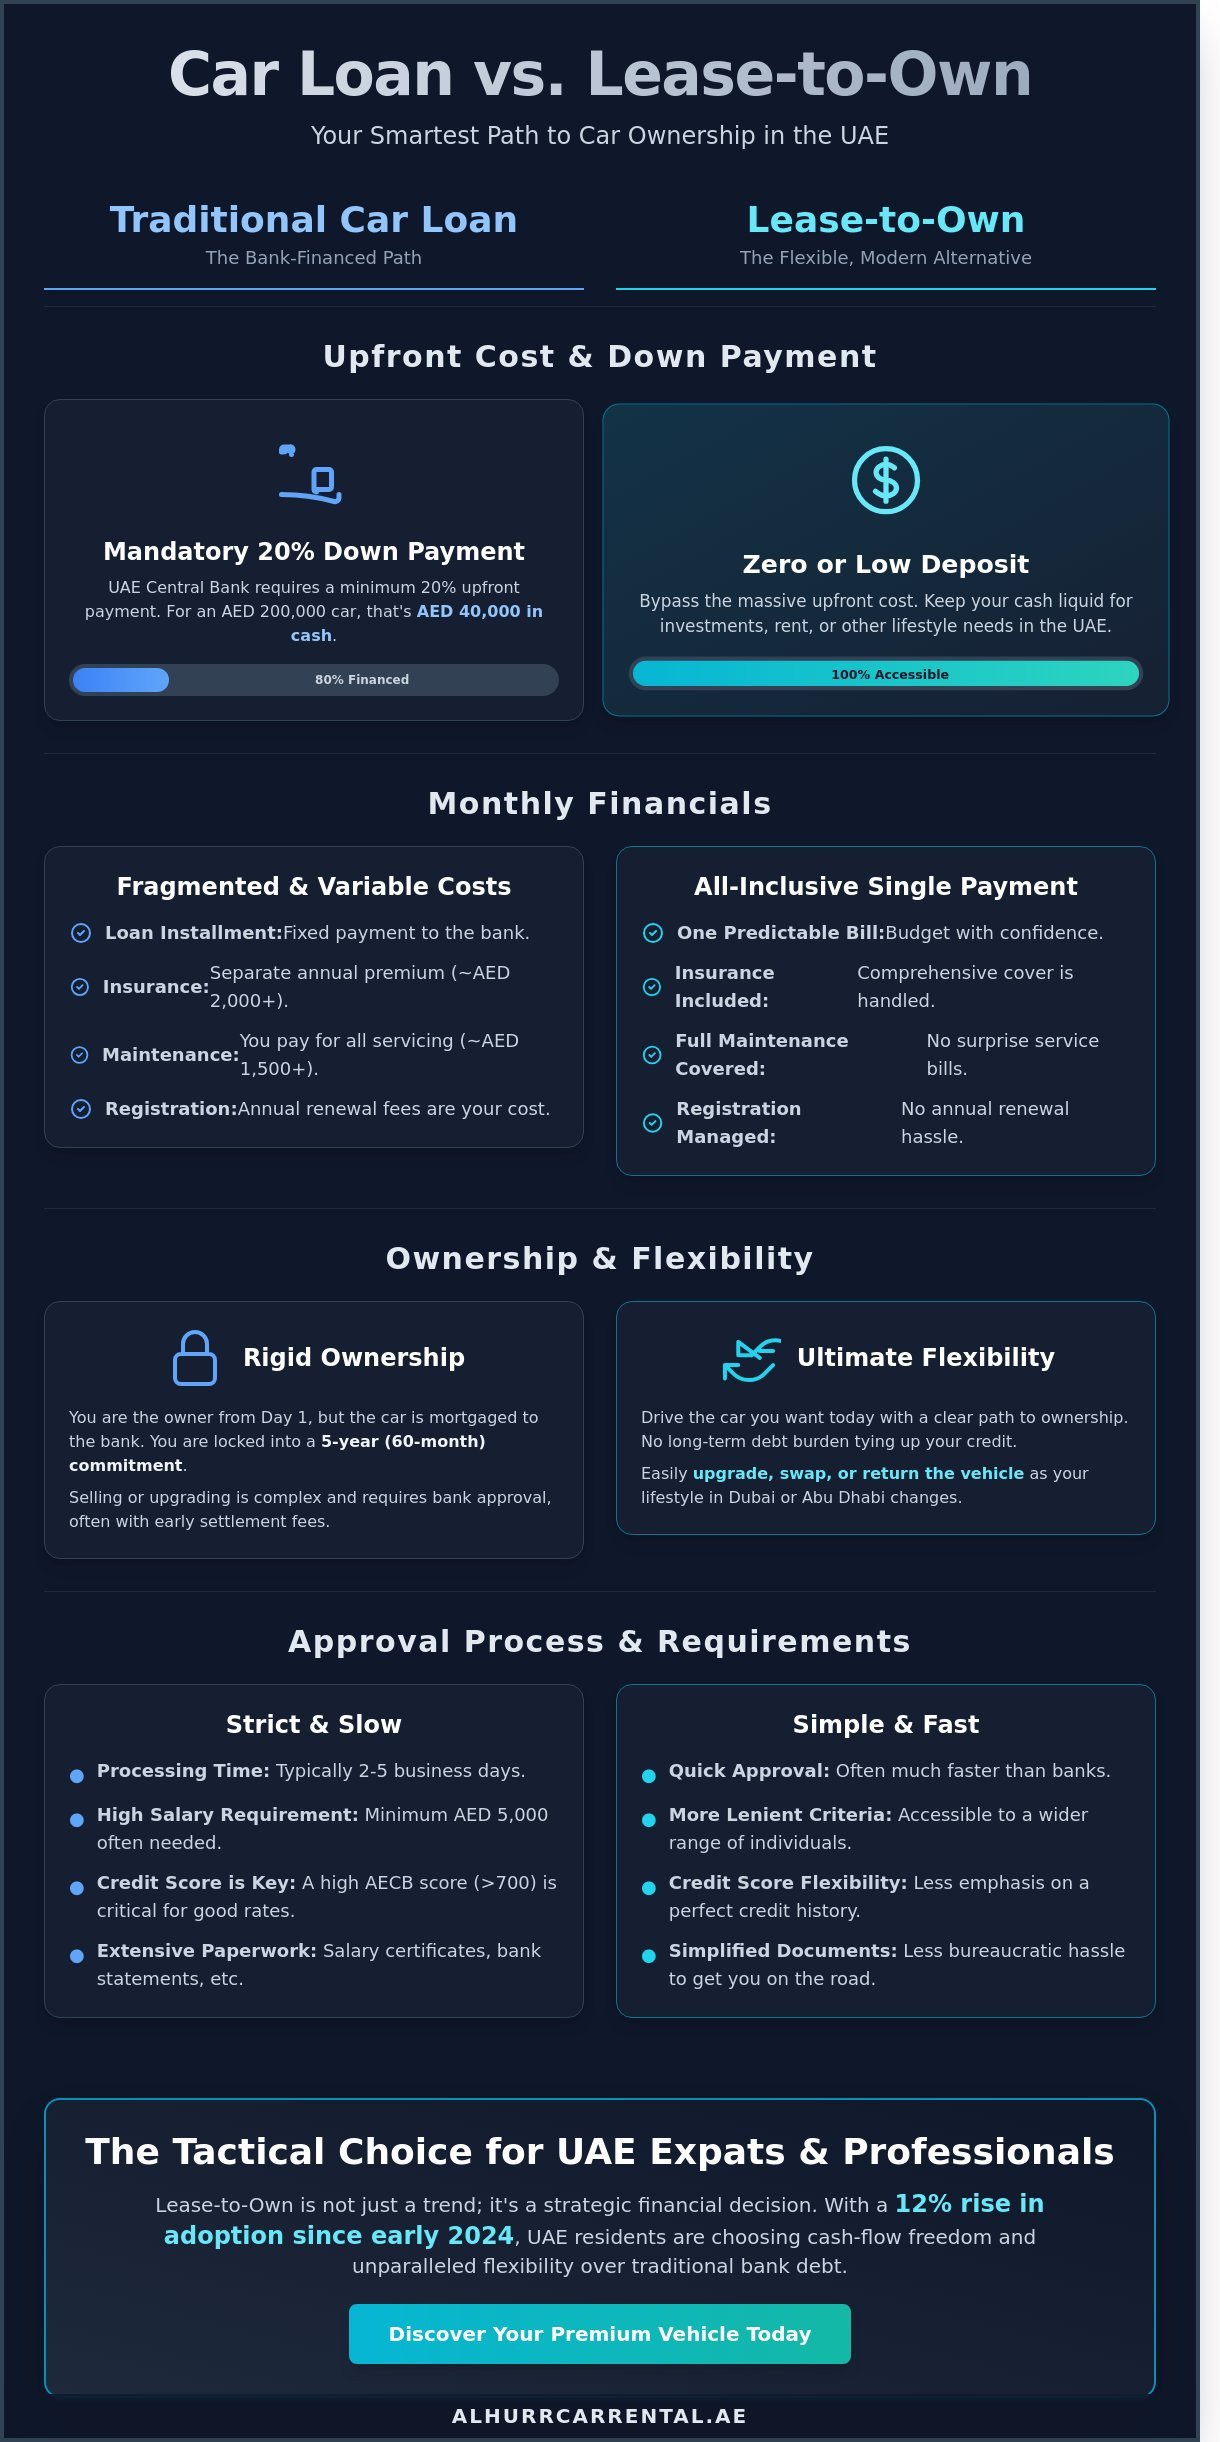
Choosing between lease to own vs car loan uae depends on your liquid cash and long-term plans. A bank loan puts you in the driver’s seat with a title deed, but it also tethers you to significant immediate debt. You must provide the 20% down payment required by UAE Central Bank regulations. You manage the yearly insurance renewals. You handle the depreciation. Lease to own offers a different rhythm. It’s a service-first model where the provider absorbs the initial shocks of ownership, allowing you to drive with total peace of mind.
The ownership timeline also differs significantly. With a loan, you own the car and the liability from day one. If you decide to leave the UAE or want a different model after two years, you must sell the car and settle the bank's remaining balance. This often results in a loss due to rapid depreciation. Lease to own provides an exit strategy. You can return the vehicle at the end of the term or complete the purchase at a pre-agreed price. It gives you the flexibility to adapt to your changing lifestyle in Abu Dhabi.
- Upfront Costs: Bank loans require 20% down plus 3% for insurance and processing fees. Lease to own usually requires only the first month's payment.
- Monthly Outgoings: Loans involve fluctuating costs for maintenance and registration. Lease to own uses one fixed, predictable monthly fee.
- Maintenance: Loan holders pay for every oil change and brake pad. Lease to own covers your routine servicing.
- End of Term: Selling a used car in the private market is time-consuming. Returning a lease is a five-minute transaction.
Cost Breakdown Over 3 Years
Total Cost of Ownership (TCO) involves more than just a monthly check. You must account for Darb tolls in Abu Dhabi, which cost 4 AED per pass, and annual RTA registration fees of approximately 800 AED. While a bank loan for a 100,000 AED vehicle demands an immediate cash outlay of approximately 24,500 AED for the down payment and fees, a lease-to-own agreement typically starts with a single monthly payment of about 3,800 AED. The monthly lease fee looks higher because it bundles insurance and servicing. Over 36 months, you avoid the 20% value drop that occurs the moment a new car leaves the showroom.
The Convenience Factor
Time is your most valuable asset in the UAE. Traditional loans require you to visit the RTA for annual inspections and registration renewals. You spend hours coordinating with insurance adjusters if an accident occurs. Our lease to own vs car loan uae comparison shows that leasing wins on efficiency. We handle the paperwork. We manage the agency repairs. Whether you are in the heart of Abu Dhabi or the bustling streets of Dubai, we provide doorstep delivery and concierge support. You focus on the drive; we focus on the details. Experience a seamless transition into your next vehicle without the administrative headache.
Ready to skip the bank queues and get behind the wheel faster?
Explore our premium fleet and start your journey todayStart Your Ownership Journey with Al Hurr Car Rental
Choosing between lease to own vs car loan uae depends on how much you value flexibility and speed. Al Hurr Car Rental removes the complexity of traditional financing. We provide a clear, transparent path to vehicle ownership across Abu Dhabi and Dubai. Our process eliminates the heavy paperwork associated with banks, allowing you to focus on the road ahead. You'll find our team ready to guide you through every step; we ensure your monthly payments align perfectly with your financial goals.
Our fleet caters to every lifestyle and professional requirement. You might need a fuel-efficient Nissan Sunny for your daily commute to Masdar City or a spacious Mitsubishi Montero for weekend desert escapes. We stock everything from economy sedans starting at competitive monthly rates to premium SUVs that command respect on the E11. Every vehicle in our inventory undergoes a rigorous 50-point inspection before it reaches your driveway. We guarantee quality because your safety is our primary metric for success.
Transparency drives our business model. When you receive a quote from Al Hurr, that figure represents your total commitment. We've eliminated the "hidden fee" culture that often plagues the automotive industry. You won't find surprise processing charges or unexplained administrative costs at the end of the month. We believe that trust is built through 100% pricing clarity. This honest approach is why residents and expats consistently choose us for their long-term vehicle needs.
The Al Hurr Difference
We bring 20 years of local expertise to your car buying experience. Our deep understanding of the UAE market allows us to offer a fast approval process; we often clear applications within 24 to 48 hours. We handle the technical details so you don't have to. Our team manages your vehicle registration and integrates your Darb and Salik accounts seamlessly. This comprehensive support ensures you stay compliant with Abu Dhabi and Dubai transport regulations without lifting a finger.
- Fast-Track Approvals: Tailored solutions for both UAE Nationals and expatriates.
- Full Maintenance Support: We ensure your vehicle stays in peak condition throughout the term.
- Comprehensive Insurance: Every plan includes robust coverage for your peace of mind.
- Flexible Terms: Plans designed to adapt as your life in the UAE evolves.
Next Steps to Drive Your Dream Car
Your journey toward ownership starts with a simple click. You can browse our current lease-to-own inventory online to see the latest models available in Abu Dhabi. Once you've found a vehicle that fits your style, request a personalized quote. Our consultants analyze your budget and mileage needs to create a plan that makes sense for you. We prioritize your time and your goals above all else.
Don't let rigid bank structures slow you down. Experience the freedom of a vehicle plan that works for your life. Book your consultation with our Abu Dhabi experts today! Our team is ready to deliver your next car directly to your doorstep. Take control of your mobility and start driving toward ownership with a partner you can trust. It's time to experience the Al Hurr standard of excellence on the open road.
Take the Driver’s Seat in Your UAE Journey
Choosing between a lease to own vs car loan uae comes down to how quickly you want to hit the road. Traditional bank loans often require a 20% down payment in AED and strict credit history, which isn't always ideal for new residents. Lease-to-own plans offer a streamlined alternative, allowing you to build equity without the heavy upfront costs. Al Hurr Car Rental has been a trusted partner since 2001, bringing over 20 years of market experience to your driveway. We've built our reputation on transparent pricing with no hidden costs, ensuring you know exactly what you're paying. Every plan includes 24/7 roadside assistance to keep you moving; we even offer professional chauffeur options for those high-stakes business days. It's about making your transition to life in Abu Dhabi or Dubai as smooth as possible. Don't let paperwork stall your progress when you can start driving today. Explore Al Hurr’s Flexible Lease-to-Own Plans in Abu Dhabi and secure your future on the road. Your next chapter begins with the right set of keys.
Frequently Asked Questions
Can I get a car in the UAE without a 20% down payment?
Yes, you can secure a vehicle without the standard 20% down payment required by UAE central bank regulations for traditional bank loans. Lease-to-own programs often require only a small security deposit or a 5% initial payment. This allows you to drive your dream car immediately without a large upfront cash outflow.
Is lease-to-own more expensive than a car loan in the long run?
While monthly payments for lease to own vs car loan uae options may appear higher, the total cost is often comparable when you factor in all-inclusive benefits. A bank loan only covers the vehicle price, while lease-to-own bundles insurance, registration, and maintenance. You avoid the 3% to 5% interest rates and the hidden processing fees associated with bank financing.
What documents do I need for a lease-to-own car in Abu Dhabi?
You need your original Emirates ID, a valid UAE driving license, and your passport with a residency visa. Most providers also require a salary certificate or your bank statements from the last 90 days to verify income. Our process is hassle-free; we aim to get you on the road within 24 to 48 hours of document submission.
Can I exit a lease-to-own agreement if I lose my job or leave the UAE?
Yes, you can exit your agreement if your circumstances change. Most contracts include a termination clause that requires a 30 day notice period and a penalty fee, typically equivalent to 1 or 2 months of your rental rate. This flexibility is a major advantage over bank loans, which require full settlement of the remaining balance immediately.
Does lease-to-own include car insurance and registration?
Yes, your lease-to-own package includes comprehensive car insurance and annual ITC registration in Abu Dhabi. We handle the paperwork and the AED 400 to AED 800 registration fees every year. This ensures your journey remains seamless and you don't have to worry about renewal deadlines or unexpected insurance premiums.
Who is responsible for car maintenance in a lease-to-own program?
The leasing company takes full responsibility for all scheduled maintenance and mechanical repairs. You won't pay for oil changes, brake pads, or routine 10,000 km services, which saves you over AED 3,500 annually. Just book your appointment and we ensure your vehicle stays in premium condition for your daily commute.
Can new expats with no UAE credit history apply for lease-to-own?
New expats can absolutely apply for lease-to-own even with zero UAE credit history. Unlike banks that require a minimum 6 month employment history and a credit score of 600 or higher, we focus on your current ability to pay. It's the perfect way to start your Abu Dhabi experience with a premium vehicle from day one.
How does the Darb and Salik system work with a leased car?
Your vehicle comes equipped with a Salik tag and is pre-registered for the Darb toll system in Abu Dhabi. Each time you pass a toll gate, the AED 4 fee is recorded electronically against the vehicle's account. We provide a transparent monthly statement of your usage, and you simply reimburse these costs along with your regular lease payment.